
TransUnion®
- Rating
- 3.2
- Downloads
- 1.00M
- Content Rating
- Everyone
TransUnion® - Screenshots
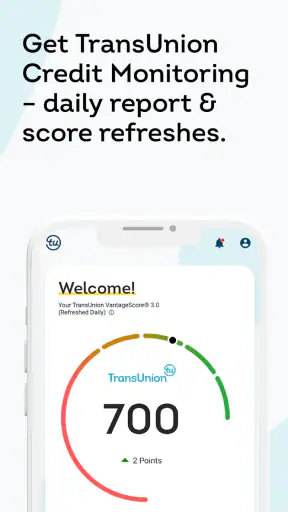
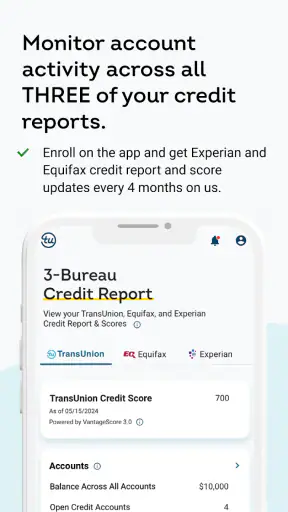
Pros
- Free access to credit scores and key credit report details.
- Credit monitoring can help detect suspicious changes early.
- Identity protection tools provide useful security alerts.
- Clean interface makes financial information easy to navigate.
- Helpful educational content explains credit-related topics clearly.
Cons
- Some features require a paid membership or subscription.
- Credit score updates may not be available in real time.
- Offers and alerts can feel frequent or promotional.
- Identity monitoring coverage may vary by plan and location.
- The app requires sensitive personal information to function.
TransUnion® - Description
- App Name
- TransUnion®
- Package Name
- com.transunion.TransUnion
- Developer
- TransUnion Interactive, Inc.
- Category
- Finance
- Last Updated
- Jan 8, 2014
- Version
- 5.8.0
When money decisions are shared across a household, credit information can become surprisingly difficult to organize. One person may be preparing for a rental application, another may be checking whether a report looks accurate, and someone else may simply want a clearer view of available financial offers. I found TransUnion® useful in that space because it brings scores, reports, and offers into one finance app instead of making me jump between separate services.
My experience was that it works best as a personal reference point rather than a complete household finance system. It can help each adult understand their own credit position and prepare for conversations about borrowing or applications, but it does not turn a shared phone into a family dashboard. That distinction matters when several people use the same device or when one person is helping another manage financial tasks.
How TransUnion® fits into everyday household money tasks
A realistic use case is a couple planning a move. One person might open the app to review their credit report before applying for a new home, while the other checks their own information separately. The value is not just seeing a score in isolation. A report gives more context, helping me think about what lenders or other businesses may see and whether the information appears consistent with my records.
I would not treat that scenario as permission to pass one account around. Credit information is personal, and the app is much easier to use responsibly when every adult keeps their own login and reviews their own details. On a shared device, I would also make a habit of signing out or handing the phone back only after closing the account area. That is a simple boundary, but it prevents an innocent convenience from becoming an unnecessary privacy problem.
The app is free, which lowers the barrier to trying it. It is aimed at Everyone, and that age classification makes it approachable for general household use, but an age label should not be confused with financial independence. A younger member of a family may be able to use the app in a basic sense while still needing an adult to explain credit, reports, offers, and the consequences of an application.
TransUnion Interactive, Inc. is the developer behind the app. It has been available since January 8, 2014, and the current version is 5.8.0. Those details suggest a long-running product rather than a brand-new experiment, although a mature app can still feel less polished in certain areas than newer personal-finance tools.
Setting up sensible boundaries on a shared phone
The first useful rule is to separate device sharing from account sharing. If a household has one phone or tablet that everyone uses, I would let each person access only their own account and avoid saving credentials where another user can reach them. I would also review the screen before showing a report to someone else, because financial information can include details that are not relevant to the conversation.
A second rule is to decide what the app is being used for before opening it. If I am checking a report for an upcoming application, I focus on reviewing the information and making notes. If I am browsing offers, I treat that as a separate activity and avoid assuming that an offer is automatically the best choice. This small separation helps prevent the attractive part of the app from distracting me from the more important record-checking work.
The app’s store summary presents scores, reports, and offers together, and that combination is convenient. It also creates a trade-off: a user may arrive looking for neutral information and quickly move toward products or recommendations. My advice is to inspect the report first, understand the purpose of an offer, and compare it with alternatives outside the app before making a decision.
For a household, I would keep a simple shared checklist rather than sharing account access. For example, each person can record that they reviewed their own report, noted questions, and agreed on the next step. The checklist should contain tasks, not sensitive account details. That gives a couple or family a way to coordinate without turning a private financial profile into a communal document.
Coordinating credit checks without mixing personal records
TransUnion® is especially useful when two adults need to prepare for the same event but have separate financial histories. A rental application, loan discussion, or major purchase may involve both people, yet one person’s score or report cannot stand in for the other’s. I found that the app works better when each user treats their review as an individual preparation step.
One practical workflow is to choose a quiet time, have each adult inspect their own information, and then discuss only the conclusions that matter for the shared decision. That might mean asking whether anything needs correcting, whether an application should be delayed, or whether more comparison is needed. There is no benefit in reading every private detail aloud when the household only needs a decision about timing or affordability.
This is also where the app’s report function is more valuable than a score alone. A single number is easy to repeat but not always useful enough to explain what needs attention. Looking through the report can reveal why a person wants to investigate further, while the other household member can do the same independently. The trade-off is time: a quick score glance is faster, but it gives a thinner basis for action.
I would not use the app as the only place to track bills, spending, or a household budget. It belongs more naturally in the credit-information part of a financial routine. A budgeting app, bank tools, or a spreadsheet may be better for cash-flow planning, recurring expenses, and shared savings goals. TransUnion® can support those decisions, but it does not replace the tools built specifically for day-to-day money management.
Another useful habit is to avoid treating an offer as a household recommendation. The right product can depend on the individual applicant, their plans, and the terms they are willing to accept. If one partner sees an offer while preparing for a shared purchase, I would use it as a prompt for comparison, not as a conclusion. This is one of the app’s less obvious trade-offs: convenience can save time, but convenience can also narrow attention.
What the app means for different ages and levels of trust
The Everyone rating makes the app broadly accessible, but credit information still needs age-appropriate explanation. For an adult, the main questions may involve report accuracy, preparation, and comparing offers. For a teenager or young adult, the more useful lesson may be understanding that a score is not a complete picture of financial health and that personal account details should not be casually shared.
I would be comfortable using the app as a teaching aid if an adult remained present and explained each screen in plain language. I would not hand over an account and assume that familiarity with a phone is the same as understanding financial consequences. The app can show information, but it cannot replace a conversation about borrowing, applications, privacy, or the difference between an attractive offer and an affordable one.
Trust is equally important between adults. A shared household does not automatically mean shared access to every report. In my view, the healthiest arrangement is voluntary sharing of relevant conclusions, with each person retaining control of their own account. That approach is less convenient than one shared login, but it is much clearer and more respectful.
People who need a formal tool for managing several profiles should think carefully before choosing this app for that purpose. I see it as centered on the individual user. It can help a household coordinate decisions, but it should not be mistaken for a family-control product or a multi-user financial workspace. Anyone expecting permissions, shared monitoring, or a combined household view may be disappointed.
Strengths, friction, and the best way to use it
The strongest part of the experience is the combination of a score and a report in a single place. That makes it easier to move from “What is my position?” to “What information supports that position?” The offers area adds another layer for users who are actively exploring financial products, although I would keep that secondary to understanding the report.
The app also benefits from being free. I can recommend trying it without asking someone to commit money before discovering whether the layout and information suit their needs. Its reach is substantial, with over a million installs, while its average rating sits at 3.2 from around eight thousand ratings. I read that as a sign that the app is useful to many people but not consistently satisfying for everyone.
The friction comes from the subject matter as much as from the interface. Credit information is not something I want to skim carelessly, especially on a small screen or while another person is waiting to use the device. The app is convenient, but convenience does not remove the need to read carefully. Users who want a very detailed, step-by-step financial education experience may prefer a dedicated educational resource alongside it.
I also think the app suits occasional check-ins better than constant checking. Opening it before an important financial decision can be sensible. Repeatedly watching a score without a clear reason may create anxiety without producing a useful action. A better workflow is to identify the question first, review the relevant information, and decide what—if anything—needs to happen next.
Compared with checking through a bank, a lender, or a general budgeting app, TransUnion® has a more focused role. A bank app may be better for transactions and balances. A budgeting tool may be better for shared spending. A lender’s process may be necessary when completing a specific application. This app is more useful when I want a dedicated view of credit-related information before taking those next steps.
That comparison also explains when I would skip it. If my only goal is tracking household expenses, I would choose a budgeting solution. If I need two people to edit one shared financial plan, I would look for a collaborative tool. If I am already using another trusted service that provides the exact report and comparison features I need, adding another app may not improve my routine.
My household verdict
After using TransUnion® as a finance companion, I would recommend it to adults who want a convenient place to review their credit score, inspect their report, and explore offers without paying for access. It is particularly practical before a major household decision, provided each person checks their own information and the final choice is based on more than an appealing suggestion inside the app.
I would recommend a little caution for shared-device households. Keep account boundaries clear, avoid passing one login around, and discuss only the information needed for the shared decision. For younger users, use the app as a guided learning tool rather than assuming that an Everyone rating removes the need for supervision and explanation.
Its overall rating of 3.2 reflects my balanced impression: the core idea is useful, but the experience is not a universal replacement for banking, budgeting, or financial advice. The app earns a place in my toolkit when I need a focused credit check, not when I need to run the entire household budget.
My bottom line: TransUnion® is worth trying if your immediate question concerns your own credit information. Use it deliberately, keep private accounts separate, compare offers carefully, and pair it with a budgeting method for the parts of household finance it does not cover. That approach lets the app do what it does best without asking it to become something it was not designed to be.
FAQ
What is TransUnion® and what can I use it for?
TransUnion® is a credit information and identity-monitoring service that helps users review aspects of their financial profile. Depending on your location and subscription, the app may provide access to credit scores, credit reports, monitoring alerts, identity-protection tools, and educational resources. It is designed to help you understand changes in your credit activity and identify potentially suspicious account or personal-information activity.
Is the TransUnion® app free to download and use?
The TransUnion® app may be free to download, but some of its features can require a paid membership, trial, or an eligible TransUnion® product. Available services, pricing, billing terms, and free features vary by country and plan. Before starting a trial or subscription, check the current in-app offer carefully, including renewal dates, cancellation rules, and whether access to reports or monitoring is limited.
What information is required to create a TransUnion® account?
To verify your identity and locate the correct credit file, TransUnion® may request personal details such as your name, address, date of birth, and other identifying information. You may also need to answer identity-verification questions or provide additional documentation in certain situations. Use only the official app and review its privacy policy so you understand how submitted information is handled and protected.
Can TransUnion® help me improve my credit score?
TransUnion® can help you understand your credit report, follow score changes, and learn which behaviors commonly affect creditworthiness, but it cannot directly repair or guarantee an improved score. The app may highlight factors such as payment history, credit utilization, account age, and recent applications. Improving credit generally requires consistent payments, responsible borrowing, and checking reports for errors or unauthorized activity.
Are TransUnion® credit scores and reports official for every lender?
TransUnion® provides credit information from its own reporting database, but lenders may use different credit bureaus, scoring models, and versions of a report when evaluating applications. As a result, the score displayed in the app may differ from a score seen elsewhere or from the score used by a particular lender. Treat the information as useful guidance, while checking the lender’s requirements directly.


